General Liability
Injuries to customers, on the premises and away from it.
Each year, roughly 1 in 6 Americans (or 48 million people) get sick, 128,000 are hospitalized, and 3,000 die of foodborne diseases.
- Bodily Injury
- Slips and Falls
- Property Damages
- Product Liability
- Cuts and Bruises
- Burns and Broken Teeth
The Commercial General Liability Policy provides the insurance protection needed to pay for injuries to customers.
The policy also covers accidents occurring on the premises or away from the premises. In addition to the limits, the policy provides supplemental payments for attorney fees, court costs, and other expenses associated with a claim or the defense of a liability suit.
Contact us about this coverage
Liquor Liability
Claims for harm caused after a drink was served, also called dram shop.
Why buy liquor liability insurance? Coverage up to $1,000,000!
- A patron who drank elsewhere is served one drink, then causes a head-on collision driving home, and the other driver sues your establishment.
- A patron served alcohol at your bar is struck and killed walking home, and the estate alleges negligent service contributed to the accident.
- Two patrons fight, one is injured, and they sue alleging the negligent service of alcohol caused it.
Each of these is a real dram shop scenario, and each one lands on the establishment that poured the drink. We review your exposure and place the account with carriers who write this class of risk every day.
Contact us about this coverage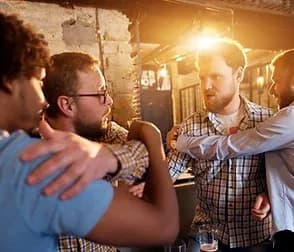
Assault and Battery
Fights, ejections, and force used by your security staff.
Around 60% of claims placed against bars and nightclubs are a result of assault and battery.
- Do you know about fight coverage?
- Employee vs. Customer: Who Will Pay?
- Does your bartender drink while working with customers?
The claims can range from customers' or employees' fights to customers claiming that the security personnel in the bar or nightclub used unreasonable force dealing with them.
Contact us about this coverage
Workers' Compensation
Kitchen, delivery, and front-of-house injuries.
The most common injuries for restaurant workers are sprains and strains, which account for one-third of all injuries reported by restaurants.
- Slips and Falls
- Cuts from Knives or Kitchen Equipment
- Auto Accidents During Delivery or Catering
- Employees Breaking Up Fights in a Bar
- Burns from Hot Liquids, Chemicals, Plates, Stoves, Ovens, or Fryers
This coverage agreement obligates the insurer to pay all compensation and other benefits required by the Workers' Compensation Law or Occupational Disease Law of any state listed in the policy.
Contact us about this coverage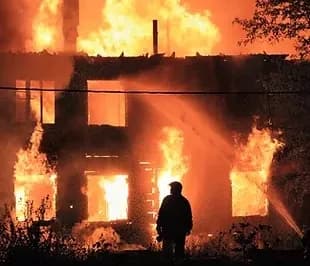
Commercial Property Coverage
Building and personal property: fire, wind, and water.
The leading cause of fire ignition for restaurants is deep fryers, ranges, and other cooking equipment. Electrical malfunction is one of the most common causes of restaurant fires.
- Fire Damage
- Windstorm Damage
- Lightning
- Water Damage from Pipes
Property is considered to be any item that has value. Property can be classified as real property (buildings) or personal property.
The insuring agreement in the Building and Personal Property Coverage Form promises to pay for direct physical loss or damage to covered property.
Contact us about this coverage
Commercial Crime Coverage
Theft, burglary, robbery, and forgery by third parties.
Even the most prepared businesses can find themselves victims of a crime.
- Do you have a warranty on your policy?
- Your alarms must be functioning properly in order to qualify to submit a claim.
Commercial Crime Coverage protects against robberies by third parties. This includes theft, burglary, robbery, and forgery, and it can protect your business from the financial risk that follows.
Contact us about this coverage
Employment Practices Liability
Wrongful termination, harassment and the complaints that follow.
Should you be worried about a bad employee who files a complaint? Employees can be fired at any time for any reason, but not for the wrong reasons.
- Acting Inconsistently
- Retaliating
- Poor Communication
- Not Seeking Advice
- Lack of Records
- Not Having Clear Termination Policies
Criminal harassment generally entails intentionally targeting someone else with behavior that is meant to alarm, annoy, torment or terrorize them. Most state laws require that the behavior cause a credible threat to the person's safety or their family's safety.
That includes stalking, menacing, inappropriate touching, and using inappropriate or sexual language.
Contact us about this coverage
Insurance Policy Audits
A second read of your audit before you pay it.
An audit makes sure you are paying the correct amount for general liability insurance, and that you are getting the right amount of coverage for your business.
A general liability insurance audit examines your business' payroll and risk exposure.
A workers' comp audit is an end-of-year review of records, conducted to ensure that your business has paid the correct premium for workers' comp insurance. It may be done by mail, phone, or in person, depending on the auditor and the business type.
Call us at the office if you have any questions about your audit!
Contact us about this coverage